The High-Income Professional's Investment Problem
Physicians, attorneys, executives, and other high-income professionals share a set of financial challenges that most real estate investment strategies don't fully address:
- Top federal marginal tax rate: 37% on ordinary income
- California (or NY/NJ) state income tax: 9.3%–13.3% additional
- Time scarcity: 50–80 hour work weeks leave no bandwidth for property management
- Accreditation: Most high-income professionals qualify as accredited investors, opening access to commercial real estate that requires larger minimum investments
NNN triple net lease properties address all four of these challenges simultaneously — which is why they've become one of the most popular investment vehicles among this demographic.
The Time Problem: Why "Passive" Actually Matters
A surgeon earning $800,000 per year has an implicit hourly rate of $400+ per hour. Every hour spent managing a rental property — fielding maintenance calls, reviewing leases, interviewing property managers, responding to tenant complaints — is time not spent generating income or enjoying life.
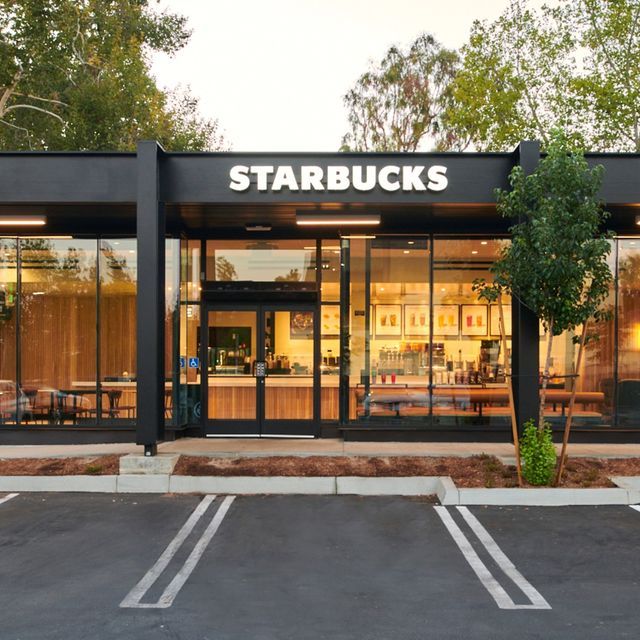
NNN investing eliminates this trade-off. An absolute NNN lease transfers all property management responsibilities — taxes, insurance, maintenance, repairs — to the tenant. The corporate tenant (McDonald's, Starbucks, Dollar General) manages everything. The landlord's only annual obligation is reviewing a rent deposit and filing a tax return.
For a physician who values their time, the difference between owning apartments (20+ hours/year per property) and owning NNN (near zero hours/year) is enormous — and the income from a well-selected NNN property is often comparable or superior once expenses are factored in.
Tax Questions for High-Income Professionals
NNN ownership does not itself shelter professional income. Review these topics with independent tax advisers:
Depreciation
Eligible improvements may be depreciable, but depreciation expense is not automatically a net loss or an unrestricted offset. Confirm basis, asset classification, and deduction limitations.
Cost Segregation: The Accelerator
A study may identify eligible components with shorter recovery periods. Ask your study provider and tax advisers about:
- Ownership of improvements, land allocation, and the actual depreciable basis
- Current-law eligibility, percentages, dates, elections, and state conformity
- Passive-activity, at-risk, basis, and other limitations on using deductions
Real-estate-professional status involves multiple tests and separate material-participation questions. Hours alone do not establish an ordinary-income offset. Independent tax advisers should determine qualification and deduction usability.
The 1031 Exchange Strategy for High-Income Investors
Many physicians and professionals eventually own real estate accumulated over their career — rental properties, commercial buildings, or land. When they sell these appreciated assets, the capital gains tax bill can be devastating: a California physician selling a $3M property with $2M in gains might owe $600,000–$800,000 in combined federal and state capital gains taxes.
A qualifying 1031 exchange may defer eligible gains when its requirements are met. Confirm eligibility, boot, financing, deadlines, basis, residency, and state rules with your QI and tax advisers; acquiring an NNN property does not automatically eliminate liability.
The Wealth-Building Model for Professionals
The most effective wealth-building strategy for high-income professionals using NNN real estate typically follows this progression:
- Initial acquisition: Purchase one or two NNN properties (typically $1.5M–$3M each) using a combination of cash and commercial financing
- Individual tax review: Evaluate any proposed study, eligible components, deduction use, and later recapture with tax advisers
- Passive income accumulation: Collect corporate-guaranteed rent checks monthly, compounding wealth without management time
- Financing review: Evaluate refinancing costs, collateral, cash flow, and loan risk with your lender; tax advisers confirm any transaction-specific consequences
- Disposition options: Compare hold, sale, and qualifying exchange options; each transaction requires individual review
- Succession questions: Ask independent estate counsel and tax advisers to assess ownership, trusts, basis, and transfer taxes
What Makes a Good First NNN Property for a Professional?
Physicians and professionals typically prioritize the following criteria for their first NNN acquisition:
- Investment-grade tenant: McDonald's, Starbucks, CVS, Walgreens — corporate guarantees with minimal credit risk
- Long lease term: 10+ years remaining to avoid near-term renewal uncertainty
- Management-free structure: Absolute NNN lease with no landlord responsibilities
- Geographic diversification: A property in a growth market outside the investor's home state, reducing concentration risk
- Price point: Most professionals start in the $1.5M–$4M range, using 65%–70% financing and deploying $500K–$1.5M in equity
Common Mistakes High-Income Investors Make
- Chasing cap rate alone: A 7.5% cap rate on a struggling regional tenant can be far riskier than a 5.0% cap rate on a McDonald's. Yield must be evaluated relative to credit quality and lease structure.
- Ignoring remaining lease term: A NNN property with 2 years left on the primary lease is not truly passive — it's a real estate redevelopment problem in disguise.
- Assuming a study always pays: Review study costs, eligible assets, deduction usability, and later recapture before commissioning it.
- Not coordinating with tax advisers: Property-specific basis and individual limitations matter; include independent tax professionals in the acquisition team.
Ready to Invest?
Discuss your property criteria, compare NNN lease economics, and plan your search with The ESS Group as your buyer's broker.